
Contractor Financing Options: How to Offer Payment Plans and Close More Jobs (2026)
By SubcontractorHub Editorial Team·Published June 2026·Updated September 2026·9 min read·Category: Contractor Business
Why Offering Financing Closes 20–35% More Jobs
The number one reason a homeowner tells a roofing, solar, or HVAC contractor “let me think about it” has nothing to do with trust, timeline, or materials. It's sticker shock at the total price.
A $14,000 roof replacement is a gut-punch. A $187/month payment on a 10-year term — less than a car payment — is a conversation. That shift in framing is the single most reliable close-rate lever available to contractors in 2026, and the data backs it up: contractors who actively present contractor financing options at the point of sale close 20–35% more jobs than those who only quote the total price. Some solar teams report close rates above 40% when financing is woven into the in-home presentation from the start.
The opportunity is large and the barrier to entry is lower than most contractors realize. You do not need to carry the loan yourself. You do not need a finance department. You need a lender relationship, a proposal tool that surfaces the monthly payment on screen, and reps who know how to lead with the monthly number rather than burying it at the bottom of a PDF.
This guide covers the types of contractor financing options available in 2026, how to present customer financing effectively at the door, the lenders SubcontractorHub integrates with directly, and what embedded financing in a proposal tool actually looks like in the field.
Types of Financing Contractors Can Offer
Not every financing type works for every trade or every job size. Here is a practical breakdown of the main contractor financing options in 2026, from third-party lenders and home improvement loans to PACE and in-house payment plans:
| Type | Best For | Typical Rate | Setup Complexity |
|---|---|---|---|
| Third-party lender (Goodleap, Sungage, Lendica) | Solar, HVAC, roofing — any size job | 5.99–15.99% APR depending on term and lender | Low — lender handles underwriting; contractor gets paid upfront |
| PACE financing | Solar + energy-efficient improvements; some roofing | Varies by state; attached to property tax | Medium — requires state eligibility, title process |
| Credit card / BNPL | Small repair jobs under $5,000 | 0% promotional periods; then 18–29% APR | Very low — homeowner manages independently |
| In-house payment plans | High-trust, repeat customers; commercial accounts | Whatever terms you set | High — you carry the receivable and the risk |
For most roofing, solar, and HVAC contractors, third-party lender financing is the highest-leverage option. The lender carries the risk, the homeowner pays the monthly bill, and you receive the full job amount within days of installation completion. The mechanics are straightforward; the hard part is building the financing presentation into your sales process so reps use it consistently.
Home improvement loans through lenders like Goodleap offer fixed monthly payments and a defined loan approval process that homeowners find easier to navigate than a line of credit or revolving account. For jobs between $8,000 and $60,000 — the typical range for a full roof, HVAC system, or solar install — a home improvement loan structures the deal cleanly and eliminates the uncertainty of a variable-rate line of credit.
PACE financing is worth understanding if you are in a PACE-eligible state and doing significant solar or energy-efficiency work. The repayment is attached to the property tax bill, which appeals to homeowners who plan to stay in the home long-term. The title and documentation process adds steps, but for larger solar installs — $20,000 to $60,000+ — the deal size justifies the friction. In-house payment plans should be reserved for established commercial relationships where you have the cash flow to carry receivables and the track record to assess credit risk yourself. Invoice factoring is another option some contractors use to free up cash flow between job milestones, though it works better for commercial accounts than residential jobs.
Presenting contractor financing options at the kitchen table dramatically improves close rates by reframing the total cost as a manageable monthly payment.
How to Present Financing to Homeowners — and Why Most Reps Get It Wrong
Most contractors who have a lender relationship still leave money on the table because of how they introduce financing. The most common mistake: mentioning financing as an afterthought after the homeowner has already reacted to the total price. By then, the objection is anchored and the monthly payment feels like a consolation prize rather than the natural way to think about the project.
Here is the presentation sequence that closes more jobs:
- Lead with the monthly payment, not the total price. Open the proposal by saying “most of our customers cover this for around $187/month.” Once the homeowner's mental model is built around a monthly number, the total price is context rather than a shock.
- Anchor to something they already pay every month. For HVAC and solar, the electric bill comparison is your most powerful tool. “Your current electric bill averages $210/month. After this system and the federal tax credit, your combined payment is $187/month and you own the equipment.” That math is self-closing.
- Present gross price and net price after incentives. For solar, always show the gross system cost, the federal ITC (currently 30%), and the net-of-incentives cost before calculating the monthly payment. Homeowners who see the $6,000 tax credit become committed to the project because walking away means leaving government money on the table.
- Offer two or three terms, not one. Show a 5-year term and a 10-year term side by side. Letting the homeowner choose between $287/month and $187/month is far more effective than forcing them to say yes or no to a single option. The psychology of choice converts better than a single ask.
- Run the application before you leave. The biggest leak in contractor financing options programs is the “send me the info and I'll apply online” close. That converts at a fraction of the in-home rate. If your proposal tool supports it, run a soft credit pull on the spot and have the loan approval in hand before you shake hands at the door.
The tools that make this sequence possible — not just the lender relationships, but the proposal software that surfaces the monthly payment on screen, runs the application, and shows the incentive math — are what separate contractors who use customer financing to their full advantage from those who mention it as an afterthought.
Walking a homeowner through contractor financing options side by side — including monthly payment terms — before they see the total price prevents sticker shock.
See Embedded Financing in Action
EasyQuote shows homeowners their monthly payment on a tablet at the door — before they have time to say “let me think about it.”
Book a Demo →The 3 Financing Lenders SubcontractorHub Integrates With
SubcontractorHub connects directly with three financing partners. Each one is embedded in the EasyQuote proposal flow — no separate portal, no manual data re-entry, no phone call to a finance desk. The rep builds the proposal, the homeowner sees the monthly payment, and the application is submitted from the same screen.
Goodleap
Goodleap is one of the largest residential solar and home improvement lenders in the country, with over $27 billion funded. Their product catalog covers solar loans, roofing, HVAC, windows, and battery storage — making them one of the few lenders who can finance a bundled solar-plus-storage-plus-roof deal under a single application. Goodleap's contractor onboarding is streamlined, their loan approval rates are strong, and their loan terms range from 5 to 25 years. For contractors working across trades or doing solar with roofing add-ons, Goodleap is the primary recommended lender. See our full Goodleap integration page for details on how it connects with SubcontractorHub.
Sungage Finance
Sungage Finance specializes in solar lending and is known for competitive rates and a clean application experience for homeowners. Where Sungage differentiates is on loan products designed around the federal ITC — their True No Fee loans don't require the homeowner to make a balloon payment or refinance when the tax credit is applied. For solar-only contractors where the financing conversation centers on the 30% ITC and the net-of-incentives monthly payment, Sungage is a strong fit. See how SubcontractorHub connects to Sungage on the Sungage Finance integration page.
Lendica
Lendica focuses on working capital and contractor-side financing — products that help contractors manage cash flow between job completion and homeowner payment, rather than financing the homeowner directly. For roofing and HVAC contractors who need bridge funding to cover material costs before the job starts, or who want to offer extended payment terms to commercial clients without carrying the receivable themselves, Lendica fills a gap that consumer-facing solar lenders don't address. Unlike a traditional line of credit, Lendica's working capital products are tied directly to job data, so funding scales with your project volume. The Lendica integration in SubcontractorHub connects financing to the project record, so cash flow management is visible in the same platform as the job itself. Learn more on the contractor financing overview page.
Financing changes the answer most in the $15,000–$80,000 band, which is where most remodeling and home improvement projects land. If that is your ticket size, how to price a remodeling job covers the markup arithmetic the payment is calculated from, and our remodeling software guide compares the platforms that present financing inside the proposal itself.
Installment Payment Platforms, Financing Widgets, and Checkout Integrations
Once you have chosen a lender, you still have to choose how the financing reaches the homeowner. Vendors describe the same underlying loan in four different ways — an installment payment platform, a financing widget, checkout financing, or a financing marketplace — and the labels are not interchangeable. They live in different places in your sales process and they are good at different things. Picking the wrong shape is the most common reason a contractor financing program gets signed and then never used.
| Integration Shape | Where It Lives | Best At | Trade-off |
|---|---|---|---|
| Installment payment platform | Lender-side portal or API; the loan product itself | Turning a lump-sum invoice into fixed monthly installments the homeowner can budget | On its own it is a portal your reps must remember to open |
| Financing widget | Embedded on your website, landing page, or estimate PDF | Capturing prequalified interest before a rep is ever dispatched | A website widget generates leads, not signatures — it does not close the job |
| Checkout financing (point of sale) | Inside the proposal, at the moment of signature | Converting the homeowner while the rep is still in the room | Requires the proposal tool and the lender to be genuinely integrated |
| Financing marketplace | One application routed to several lenders at once | Approval rates — a decline from one lender can still be an approval from another | More parties to reconcile; funding timelines can vary by lender |
These are additive, not exclusive. The strongest setup we see runs a financing widget on the website to warm up inbound leads, and checkout financing inside the proposal to close them — both drawing on the same installment loan product from the same lender, so the homeowner is never re-underwritten and your office is not reconciling two systems.
Installment Payment Platforms for Electrical and Home Improvement Contractors
Roofing, solar, and HVAC jobs are large enough that a homeowner expects to discuss financing. Electrical contractors and general home improvement companies work a different ticket band — a panel upgrade, an EV charger, a bathroom remodel, a lighting retrofit — where the job is often $2,000 to $25,000 and the homeowner arrived expecting to pay by card. That band is exactly where an installment payment platform earns its keep: it is the difference between a homeowner deferring a $9,000 panel upgrade and approving it at $155 a month.
Two practical notes for smaller-ticket trades. First, installment financing has to be quoted at the same moment as the price, not offered after the homeowner hesitates — once someone has said “let me think about it,” a monthly payment reads as a sales tactic rather than an option. Second, the arithmetic only works if your pricing already carries the program cost; if you are sizing that, our contractor markup calculator and business loan calculator cover the markup and payment math respectively. Electrical contractors pricing panel and service work can start from the electrical panel upgrade cost calculator.
What a Contractor Financing Program Costs You
Homeowner-facing financing is not free to the contractor. The homeowner sees an APR; you pay a dealer fee (sometimes called a merchant fee or discount fee) that is deducted from the amount the lender funds you. The structural relationship is consistent across lenders and worth understanding before you compare programs: the more attractive the homeowner's terms, the higher the dealer fee. A market-rate APR carries the lowest fee; a long low-APR promotion carries more; and “same as cash” or deferred-interest promotions — where the homeowner pays no interest if they clear the balance inside the promo window — typically carry the highest, because the lender is recovering the subsidized interest from you rather than from them.
Ask any prospective partner for the fee on each promo tier in writing, and confirm it against your own margin rather than the tier your competitor advertises — fee schedules are negotiated per contractor and vary with volume, so a published number is a starting point, not a quote. Our guide to no dealer fee contractor financing works through how the fee erodes margin and when a no-fee program is genuinely the better deal. If you would rather see the whole flow — quote, payment options, and signature in one pass — the SubcontractorHub proposal and sales velocity toolkit is where the financing sits inside the sale.
How SubcontractorHub Embeds Financing in the Proposal
The most common failure mode in contractor financing options programs is operational: the lender relationship exists, the rates are competitive, but reps don't use it consistently because the workflow is cumbersome. The rep builds the proposal in one tool, then switches to a lender portal, re-enters the job details, runs the credit application, and comes back to the proposal screen. That context switch kills momentum in an in-home sales presentation.
SubcontractorHub's EasyQuote eliminates that gap. The rep builds the proposal on a tablet — entering the scope of work, materials, and pricing — and the financing options appear as part of the same screen. The homeowner sees the project details, the total price, and the monthly payment options side by side. If they want to apply, the rep initiates the application directly from the proposal, the soft credit pull happens in seconds, and the approval status comes back before the presentation is over.
The rep never leaves the proposal screen to call a finance desk. The homeowner never has to “go online later to apply.” The entire financing step — from presentation to approval — happens at the kitchen table, in the driveway, or at the door, while the job is still top of mind.
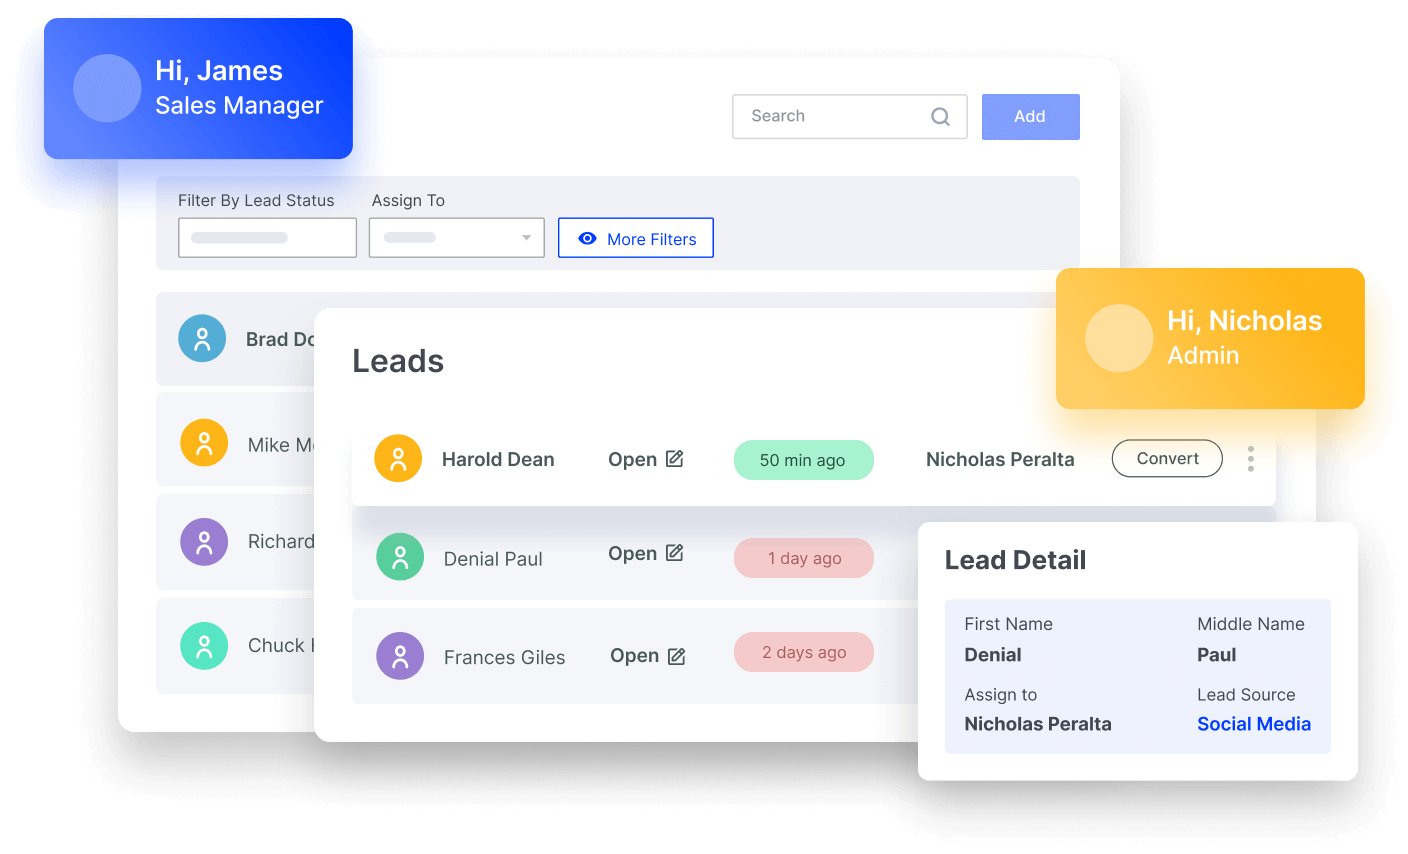
EasyQuote: financing options embedded in the proposal — no portal switching, no finance desk calls
For solar contractors, EasyQuote calculates the net-of-incentives price automatically — showing the gross system cost, the federal ITC reduction, and the net price — and then displays the monthly payment on that net figure. Homeowners see the full picture in one view rather than having to trust the rep's arithmetic on a napkin.
For roofing and HVAC, the same logic applies: present the project total, surface the monthly payment, and let the homeowner choose their term before objections can form around the sticker price.
The result is a financing program that actually gets used — consistently, across every rep, on every job — because it requires zero extra steps from the sales workflow the team is already running. Learn more about contractor financing options in SubcontractorHub.
Streamlined contractor financing options with same-day loan approval help homeowners commit at the door rather than delaying the decision.
Frequently Asked Questions
What is contractor financing?
Contractor financing is a program that lets homeowners pay for a roofing, solar, or HVAC installation over time through monthly payments instead of a lump sum. The contractor partners with a third-party lender — like Goodleap, Sungage, or Lendica — who funds the job upfront and collects from the homeowner. The contractor gets paid in full at job completion; the homeowner gets a manageable monthly payment.
How do roofing contractors offer financing?
Roofing contractors offer financing by partnering with a lender, integrating that lender into their proposal software, and presenting the monthly payment option alongside the total project cost at the homeowner's door. The best setup embeds financing directly into the proposal tool so reps can run a soft credit check and get a rate on the spot — without leaving the sales conversation to call a finance desk.
What financing options are available for HVAC contractors?
HVAC contractors can access third-party lender financing through partners like Goodleap and Lendica, manufacturer financing programs offered through equipment distributors, PACE financing in states where it's available for energy-efficient upgrades, and in some cases credit card or BNPL options for smaller repair jobs. The most effective option for closing jobs at the door is embedded third-party financing inside a proposal tool.
Does offering financing increase close rates?
Yes. Contractors who actively present financing options at the point of sale typically close 20–35% more jobs than those who don't. The primary reason homeowners delay or decline is sticker shock at the total cost. When a $14,000 roof becomes $187/month, the conversation shifts from 'I can't afford that' to 'let me check if that fits my budget' — a far easier objection for a trained rep to handle.
What is an installment payment platform for contractors?
An installment payment platform is the loan product behind contractor financing: it converts a lump-sum job price into fixed monthly installments for the homeowner while funding the contractor in full, usually within days of completion. It is most valuable in the $2,000-$25,000 ticket band common to electrical, remodeling, and general home improvement work, where the homeowner arrived expecting to pay by card. On its own it is a lender portal a rep has to remember to open, so pair it with checkout financing inside your proposal tool if you want reps to actually use it.
What is a contractor financing widget, and how is it different from checkout financing?
A financing widget is an embeddable element - typically a monthly-payment estimate or a prequalification button - that you place on your website, landing page, or estimate. Its job is to capture prequalified interest before a rep is dispatched, so it generates leads rather than signatures. Checkout financing runs the application inside the proposal at the moment of signature, which is what actually closes the job. A financing marketplace is a third shape: one application routed to several lenders at once, which raises approval rates for thin-credit homeowners. Most contractors are best served running a widget on the site and checkout financing in the proposal, both drawing on the same lender so the homeowner is never re-underwritten.
How does embedded financing work in proposal software?
Embedded financing means the monthly payment option is built directly into the proposal tool the contractor uses to generate quotes. Instead of quoting the job, then opening a separate lender portal, the rep sees financing options as part of the same workflow. In SubcontractorHub's EasyQuote, the rep builds the proposal on a tablet and the homeowner sees the monthly payment alongside the project scope and total price — all before the rep leaves the front door.
Related Resources
- → Contractor Financing — Finance It
- → No Dealer Fee Financing for Contractors: Protect Your Margin
- → Goodleap Financing for Contractors
- → Sungage Finance for Solar Contractors
- → SubcontractorHub for HVAC Contractors
- → SubcontractorHub for Roofing Contractors
- → HVAC Contractor Software
- → Best Solar Financing Software in 2026
- → Solar Contractor CRM
- → Best Contractor Proposal Software in 2026
- → How to Create Customized Contractor Proposals
- → Business Loan Calculator — Payment, Interest & Total Cost
- → Contractor Labor Burden Calculator — True Cost of a Field Employee
- → Contractor Markup Calculator — Markup vs. Margin by Trade
SubcontractorHub
See How Top Contractors Close More Jobs
AI proposals, sales pipeline, and project management — all in one platform.
- ✓AI-powered proposals in the field
- ✓CRM built for contractor sales
- ✓Project tracking from sale to install
30 minutes. No commitment.