
The Roofing Insurance Claim Process in 2026: A Contractor's Guide to Storm Jobs and Supplements
By SubcontractorHub Editorial Team·Published July 2026 · Updated October 2026
Quick Answer
The roofing insurance claim process starts when the household contacts the carrier. Ask what is covered, the deductible, and whether an estimate is needed. Photograph the damage and wait for the adjuster before extensive permanent repairs. This page does not publish a week count or a revenue percent.
Storm work is a paperwork job as much as a roof job. A carrier writes an initial estimate, the crew opens the roof, and the deck, the flashing, or a code item may not match that first scope. If nobody writes down the difference, the file still shows the first scope. This page does not say that gap is a percent of revenue.
This guide walks through the roofing insurance claim process a restoration contractor can run in 2026: the sequence, what an early estimate can miss, how a supplement asks for items the first scope left out, and the photos and questions the Insurance Information Institute tells a household to keep.
The roofing insurance claim process, step by step
Every carrier has its own forms, but the underlying sequence is consistent across an insurance restoration job:
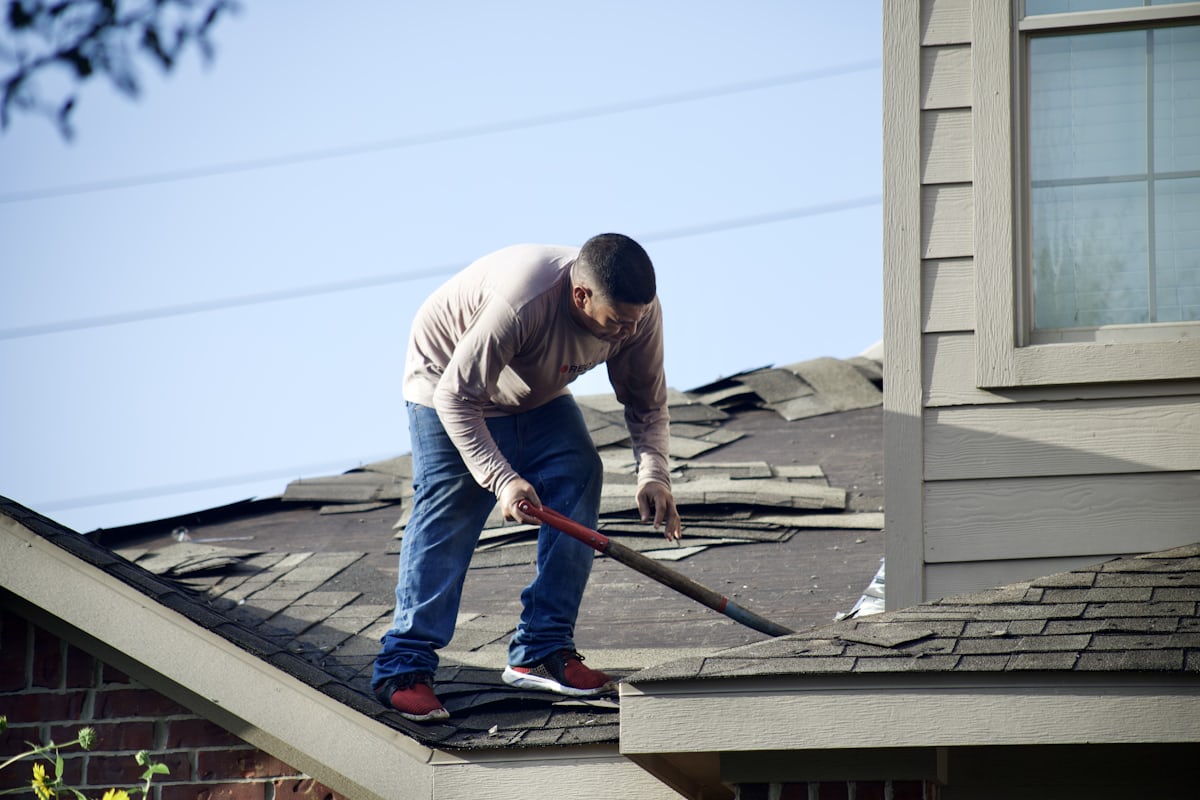
- Inspection and documentation. After a storm, you inspect the roof and document damage before anyone files anything. Photograph hail hits, wind creasing, lifted shingles, damaged flashing, and interior leaks, with dates and addresses attached to every image.
- Homeowner files the claim. The property owner reports the loss to their carrier and receives a claim number. The contractor works from that claim, not around it.
- Adjuster inspection. The carrier sends a field adjuster who inspects and writes an initial scope and estimate. Meeting the adjuster on the roof, with your own documentation in hand, is the highest-leverage 30 minutes in the whole process.
- Scope review. When the carrier estimate comes back, you compare it line by line against the true cost of a code-compliant replacement. This is where you find what is missing.
- Supplement submission. Missed or undervalued items go back to the carrier as a documented supplement.
- Approval, production, and reconciliation. Once the scope is agreed, you build the job and reconcile the final invoice against the approved amount, including depreciation released after completion.
Why an early estimate can miss the roof
A low first number is not, by itself, proof of bad faith. An estimate written from the ground, or from aerial imagery that never touches the roof, can miss what tear-off shows. This page does not state how many claims an adjuster writes in a week or how long the first visit takes. The items that often stay hidden until the roof is open are:
- Rotted or damaged decking that only appears once the old roof is off.
- Code-required upgrades — ice-and-water shield, drip edge, ventilation, or re-decking that local code now mandates on a replacement.
- Hidden flashing, valley, and chimney work that isn't visible from the ground or a photo.
- Steep, complex, or multi-story access that changes the real labor cost.
None of this means the estimate is fraudulent. It means it is incomplete — which is precisely why the supplement step exists.
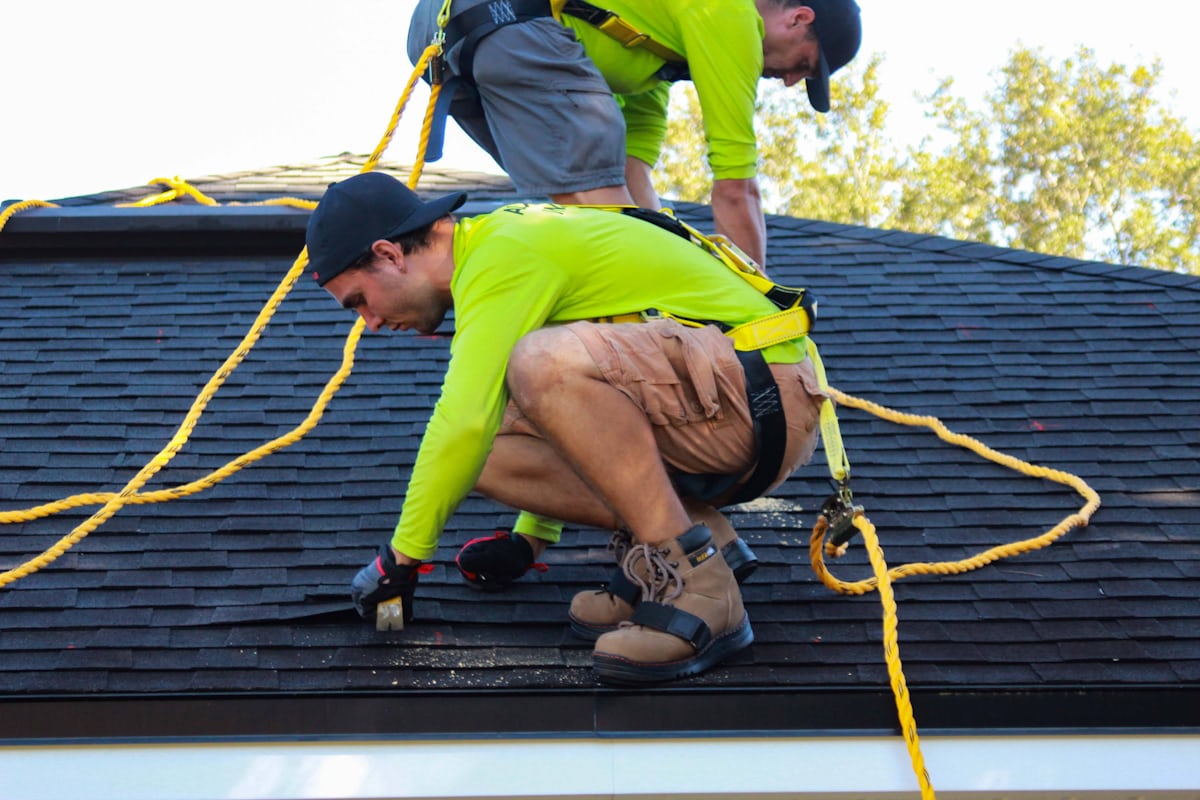
The real scope of a storm job is rarely known until the tear-off begins — which is why documentation, not the first estimate, drives the payout.
Supplements: the request after the first estimate
A roofing insurance supplement is a formal, itemized request for additional funds submitted after the initial estimate. It documents labor, materials, code items, and overhead the original scope missed. This page does not say a carrier is obligated to pay, and it does not state a percent of revenue a supplement recovers. The older version of this guide used both claims. They were not sourced, so they are gone. Ask the carrier the questions in the next section, and keep the supplement tied to a photo, a measurement, or a code citation.
A clean supplement is built on evidence, not argument. Each line item is tied to a photo, a measurement, or a code citation, and it reconciles cleanly to the carrier's own estimating format. You can size the numbers behind a claim before you write it with our roof insurance claim calculator and check your replacement math with the roofing material cost calculator.
What the roofing insurance claim process asks first
The Insurance Information Institute's article on settling claims after a disaster tells the household to contact the agent or company immediately. Ask whether the damage is covered, how long you have to file a claim, how long it will take to process the claim, whether an estimate is needed, and what the deductible is. Make temporary repairs to prevent further damage, and save the receipts. Temporary or advance payments are part of the total settlement.
The same article says not to make extensive permanent repairs until the claims adjuster has assessed the damage. Photograph or videotape the damage. Do not throw out damaged items until the adjuster has visited, unless they are a health hazard. Be wary of contractors who ask for a large upfront payment or who bid the job at a very low price. If the policy includes additional living expenses and a disaster made the home unlivable, ask the insurer about that coverage. This page does not add a week count on top of those steps.
| Step | What the Institute says | What this page does not add |
|---|---|---|
| First call | Contact the agent or company immediately | A day count |
| Temporary work | Make temporary repairs and save the receipts | A price for those repairs |
| Permanent work | Wait until the adjuster has assessed the damage | A start date for the new roof |
| The record | Photograph the damage and keep the damaged items | A promise that photos get a claim paid |
The documentation that gets claims approved
In 2026, carriers are asking for more proof, not less — high-quality photos, inspection reports, and detailed estimates. The claims that settle quickly all share the same paper trail:
- Dated, geo-tagged photos of every damaged area, captured before and after tear-off.
- A written scope of work that matches the carrier's line-item format so nothing gets lost in translation.
- Measurements and reports that back the square count and pitch, not eyeballed numbers.
- A record of every contact with the adjuster and homeowner, so a re-inspection or dispute has a timeline behind it.
The contractors who lose money on storm work are rarely the ones doing bad roofs. They are the ones whose documentation lives across a phone camera roll, three email threads, and a rep's memory — so the supplement never gets built and the depreciation never gets released.
SubcontractorHub
See How Top Contractors Close More Jobs
AI proposals, sales pipeline, and project management — all in one platform.
- ✓AI-powered proposals in the field
- ✓CRM built for contractor sales
- ✓Project tracking from sale to install
30 minutes. No commitment.
Common mistakes that cost roofers on insurance jobs
- Signing off on the first estimate. Accepting the carrier's initial scope as final is the single most expensive habit in storm work.
- Skipping the adjuster meeting. If you aren't on the roof with the adjuster, you are negotiating scope from behind.
- Thin documentation. A supplement without photos and measurements is an opinion, and carriers don't pay opinions.
- Forgetting code items. Ventilation, drip edge, and ice-and-water shield are frequently owed and frequently left out.
- Losing track of depreciation. The recoverable depreciation released after completion is real money that goes unclaimed when nobody follows up.
How software makes storm-claim work repeatable
Knowing the process is only half of it. The other half is making sure every claim, run by every rep, is documented and supplemented the same way. That is where a purpose-built platform earns its keep. With SubcontractorHub's roofing platform, photos, measurements, scopes, and adjuster communication live on the job record instead of scattered across a phone and an inbox, so the supplement builds itself from evidence you already captured. Our storm restoration software is built specifically for insurance and restoration crews.
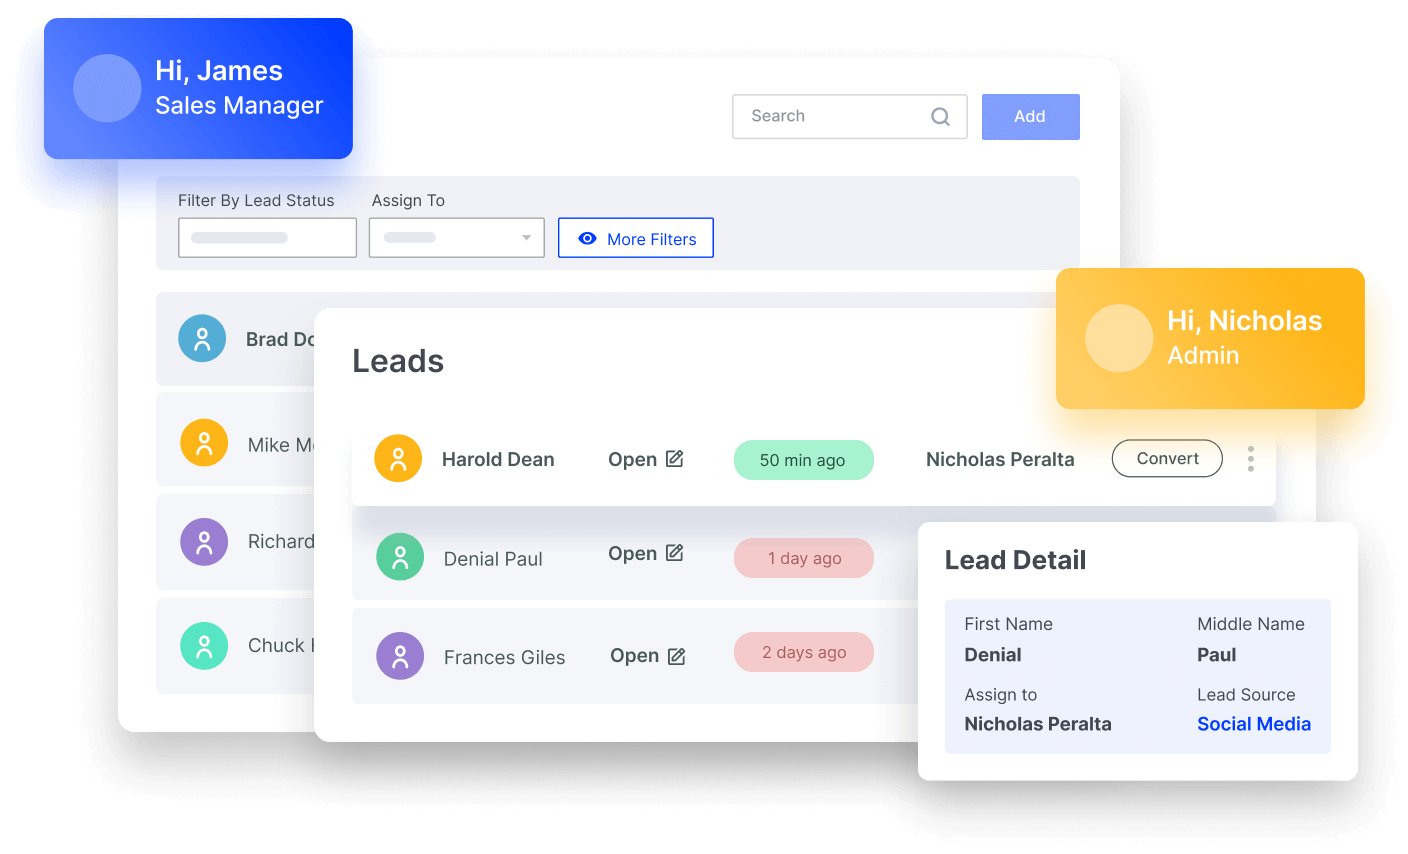
A structured scope that mirrors the carrier's line-item format means supplements reconcile the first time instead of bouncing back.
Because CRM, estimating, proposals, and project management sit in one system, the scope you document turns into a signed contract and a tracked production job without re-keying anything. Pairing an approved claim with embedded financing also lets the homeowner cover their deductible or an upgrade on a monthly payment. See the full toolset on our roofing contractor software and roofing insurance software pages.
Contractors who want more of this work should also read how to get roofing leads from insurance companies, which covers the adjuster, agent, and preferred-contractor referral channels that produce claim work — and the deductible and licensing rules that end careers.
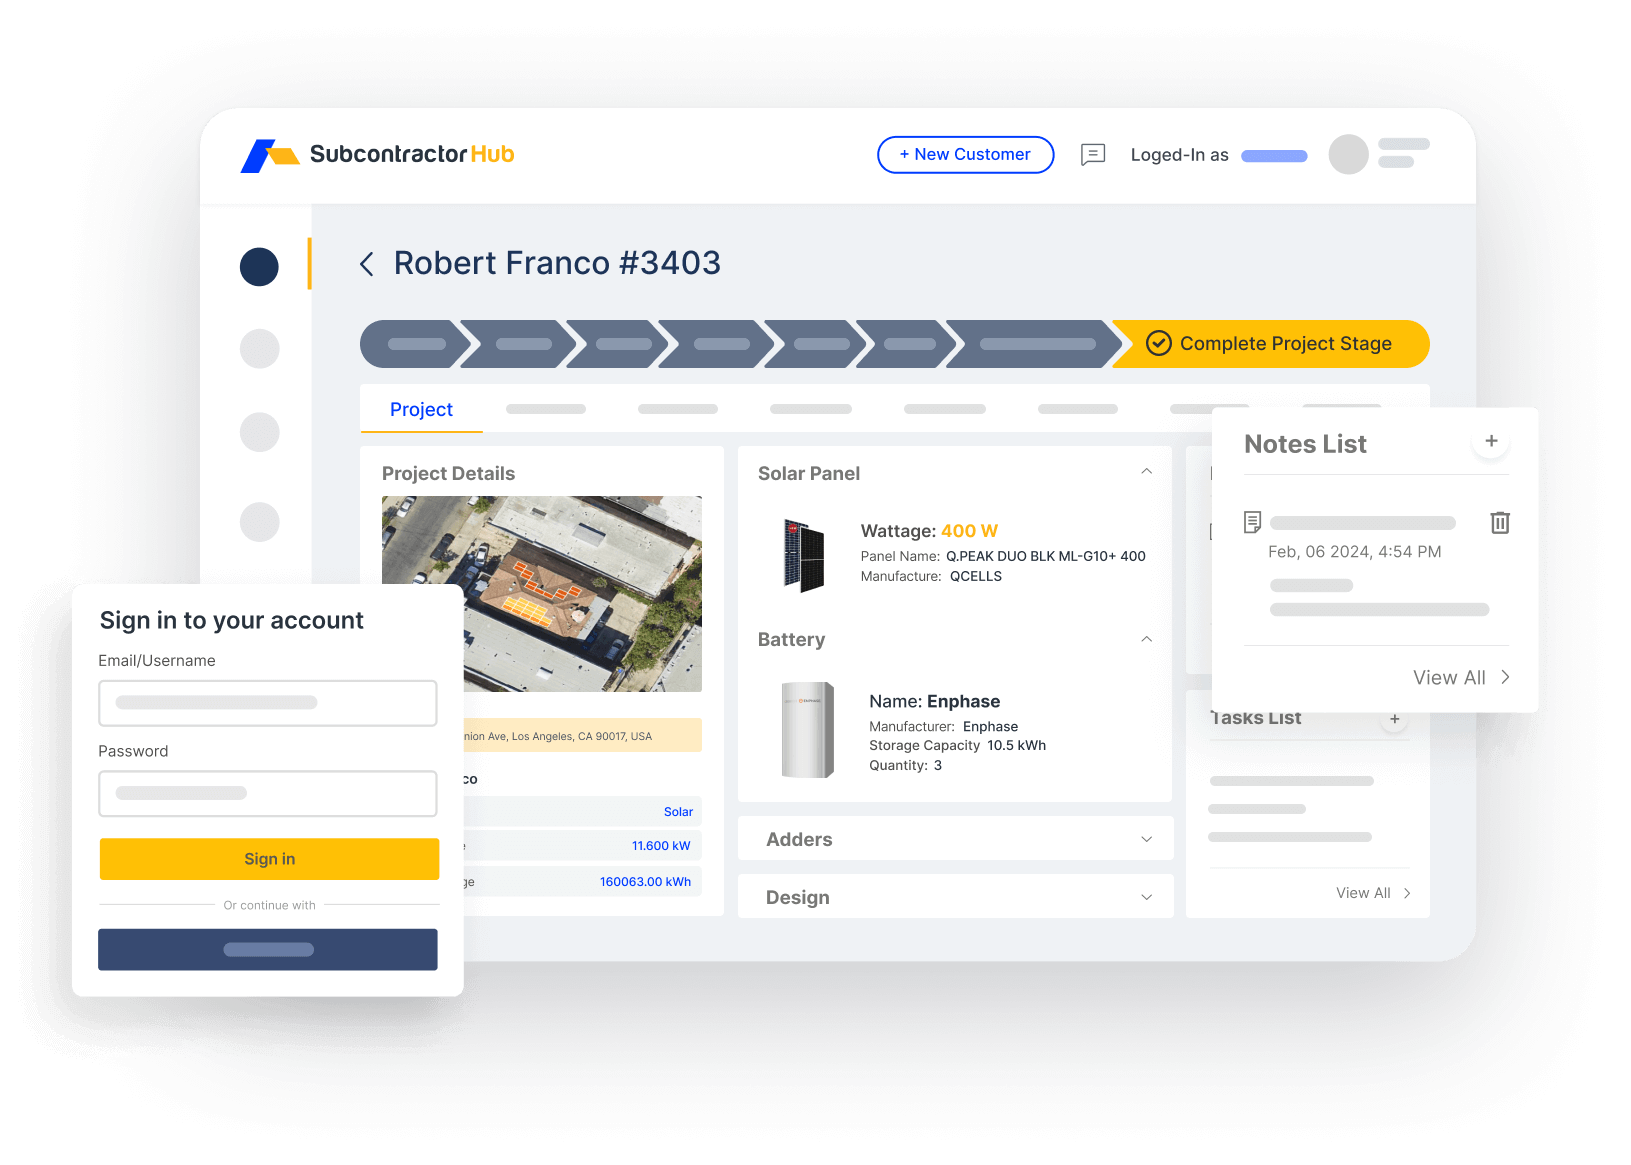
Every claim, adjuster contact, and supplement stays on one job record — so depreciation and supplements never fall through the cracks.
Frequently Asked Questions
What is the roofing insurance claim process?
It starts when a homeowner reports storm damage to their carrier. The insurer assigns a field adjuster who inspects and writes an initial scope. The contractor documents damage independently, meets the adjuster on site, then reviews the carrier's estimate for missing or undervalued items. Anything missed is submitted as a supplement with photos and documentation. Once the scope is agreed, the work is completed and the invoice is reconciled against the approved amount.
What is a roofing insurance supplement?
An itemized request for additional funds submitted to the carrier after the initial estimate. It documents labor, materials, code-required components, and overhead the adjuster's original scope missed, undervalued, or excluded. This page does not state a percent of revenue a supplement recovers, and it does not say a carrier is obligated to pay.
Why are insurance adjuster estimates usually too low?
An initial estimate can miss rotted decking, inadequate ventilation, hidden flashing, or a code item that shows up at tear-off. This page does not state how many claims an adjuster writes in a week or how long the first visit takes. An incomplete scope is why a supplement exists.
How long does a roof insurance claim take?
This page does not publish a week count. The Insurance Information Institute says to contact the agent immediately, make temporary repairs and save the receipts, and wait until the adjuster has assessed the damage before extensive permanent repairs. Photograph the damage, and do not throw out damaged items until the adjuster has visited.
Can a roofing contractor help with an insurance claim?
Yes. A contractor can inspect and document damage, meet the adjuster on site, provide a code-compliant scope, and prepare supplements for missed line items. Contractors cannot negotiate a claim as a public adjuster unless licensed, and laws vary by state, so the contractor's role is to document and substantiate the true cost of a proper repair.
Related Reading
Win More on Every Storm Job
Stop leaving supplements on the table. SubcontractorHub keeps photos, scopes, adjuster contact, and supplements on one job record — so every claim is documented and every dollar owed gets recovered. Book a demo and we'll walk a live storm-claim workflow with you in under 30 minutes.
Book a DemoRoofing Insurance, Storm Restoration, Roofing Software